The first thing anyone who takes golf betting seriously should understand about spread betting is that it is not the same product as fixed-odds betting with a twist. It is a fundamentally different mechanism — one where your potential loss is not capped at your stake, where the bookmaker’s margin works differently, and where the experience of watching a golf tournament changes completely. I have used golf spread betting selectively for years, primarily in supremacy markets where I have a strong directional view, but I would never recommend it to a punter who has not first mastered fixed-odds golf betting. The uncapped downside is not theoretical — it is a real and frequent outcome for punters who mismanage size.
How Golf Spread Betting Mechanics Work
Spread betting works by trading on an index value rather than a fixed outcome. The spread betting operator quotes a “bid” and an “offer” price for a market — say, a player’s finishing position in a tournament. You buy above the offer if you think the player will finish higher (lower position number), or sell below the bid if you think they will finish lower. Your profit or loss is the difference between your entry price and the settlement value, multiplied by your stake per point.
For a concrete example: a spread betting operator quotes Rory McIlroy’s finishing position at 8-10 in a specific tournament. You believe he will finish top 5, so you buy at 10, staking £5 per position. If McIlroy finishes 3rd, you gain (10 – 3) positions multiplied by £5 = £35 profit. If he finishes 20th, you lose (20 – 10) positions multiplied by £5 = £50. If he misses the cut and is assigned a position of 80, you lose (80 – 10) x £5 = £350. The same bet that would have cost you £5 in a fixed-odds market can lose you 70x that in a spread market if the result moves against you.
The UK regulatory framework for spread betting falls primarily under the Financial Conduct Authority rather than the Gambling Commission, because spread betting is classified as a financial product. The 2025 statutory gambling levy that changed the landscape for fixed-odds operators does not directly apply to spread betting — a distinction that matters when comparing the regulatory environment across product types. Operators offering golf spread betting in the UK must comply with FCA conduct rules, which include specific requirements around risk disclosure and client money protection.
Golf-Specific Spread Markets Worth Understanding
The most popular golf spread markets are finishing position, total tournament score (number of strokes over par), and supremacy — which measures the points difference between two players or teams over a specified match. For tournament betting, the finishing position market is the most liquid and the one most comparable to a fixed-odds outright bet in terms of the underlying prediction required.
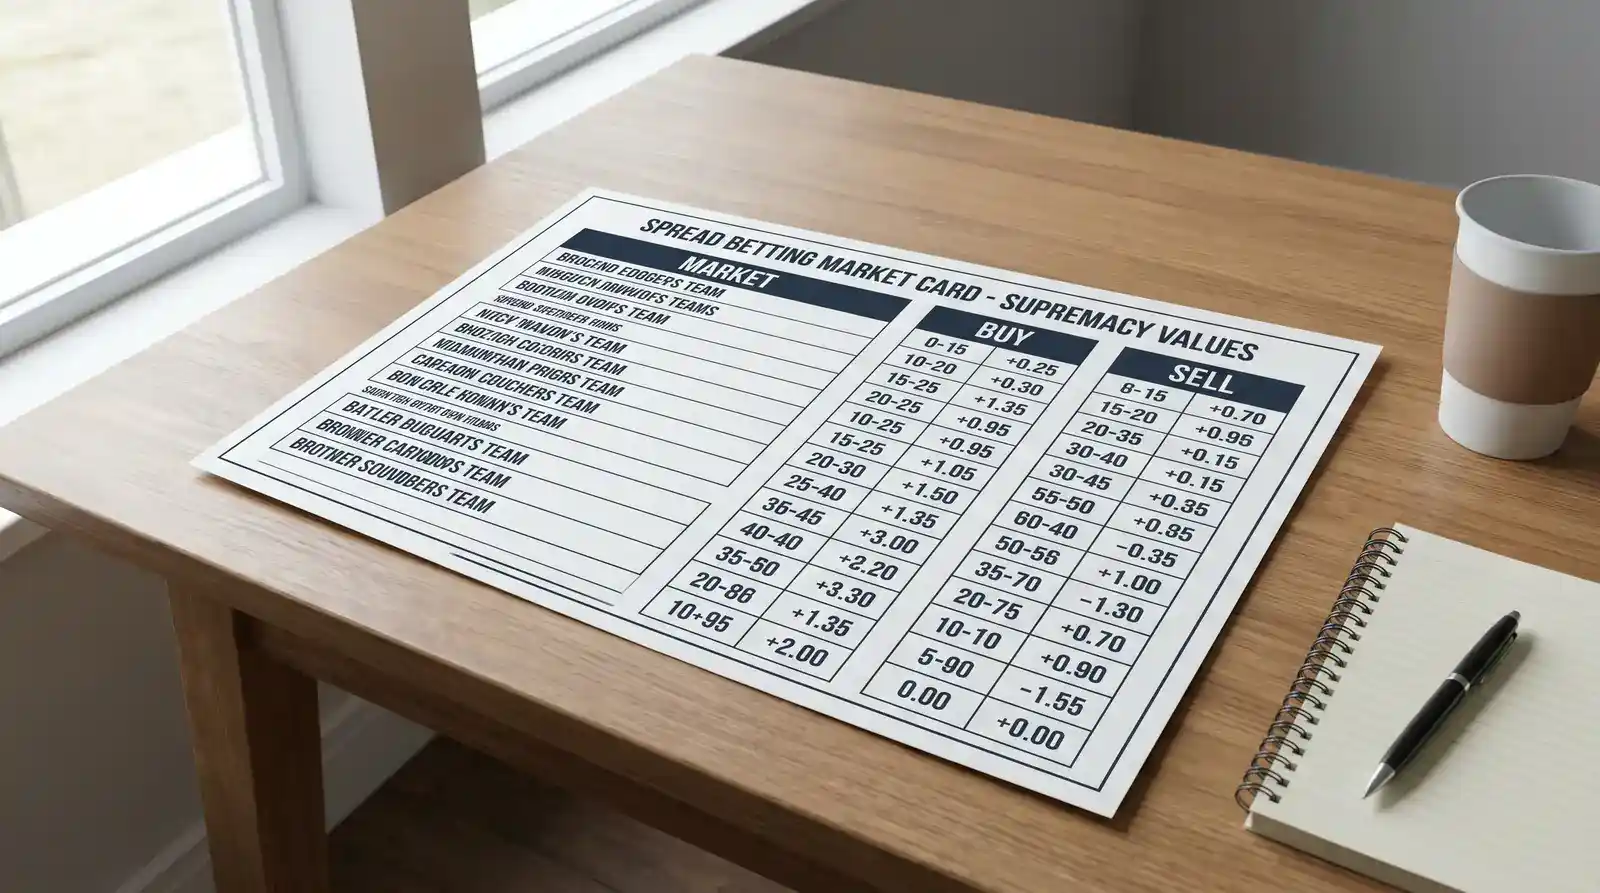
The supremacy market is where golf spread betting offers its most distinctive edge over fixed-odds. In a supremacy market between two named players, you are trading on the stroke difference between their aggregate scores over the tournament. This is conceptually similar to a matchup bet, but with an uncapped return: if you back Player A to outscore Player B and the actual stroke difference is 8 rather than the implied 2, your return is four times larger than if the actual difference was exactly 2. The flip side — if Player B outscores Player A by 8 when you backed A — is an equally large loss.
The total tournament score market — betting on how many strokes under or over par the winner will finish — is an indirect way of betting on course conditions without picking the winner. In a soft, benign week with gettable pin positions, a winning score in the mid-twenties under par is common at some PGA Tour events. In difficult Major conditions, the winning score may be even par or only a few under. Identifying which way conditions will break relative to the spread operator’s implied score is where the edge lives in total score markets.
Risk Management in Golf Spread Betting
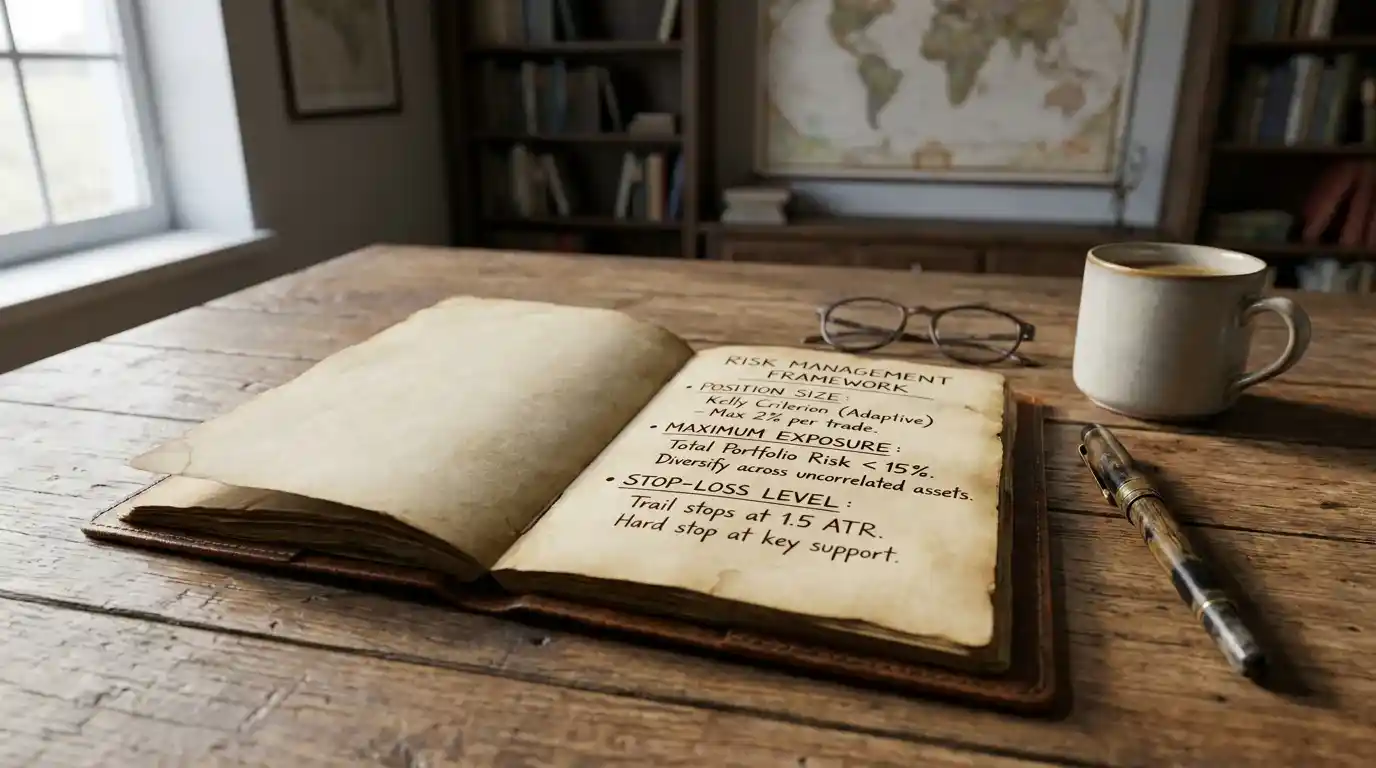
The rule I apply to all spread betting activity is non-negotiable: never open a position where the potential loss exceeds a defined percentage of my total betting bank, and always set a stop-loss before placing. Most spread betting platforms allow automatic stop-losses — a level at which the position is automatically closed to limit further losses. For golf spread betting, where scoring can move dramatically in either direction during a single round, stop-losses are not optional risk management; they are the basic requirement for responsible participation in the market.
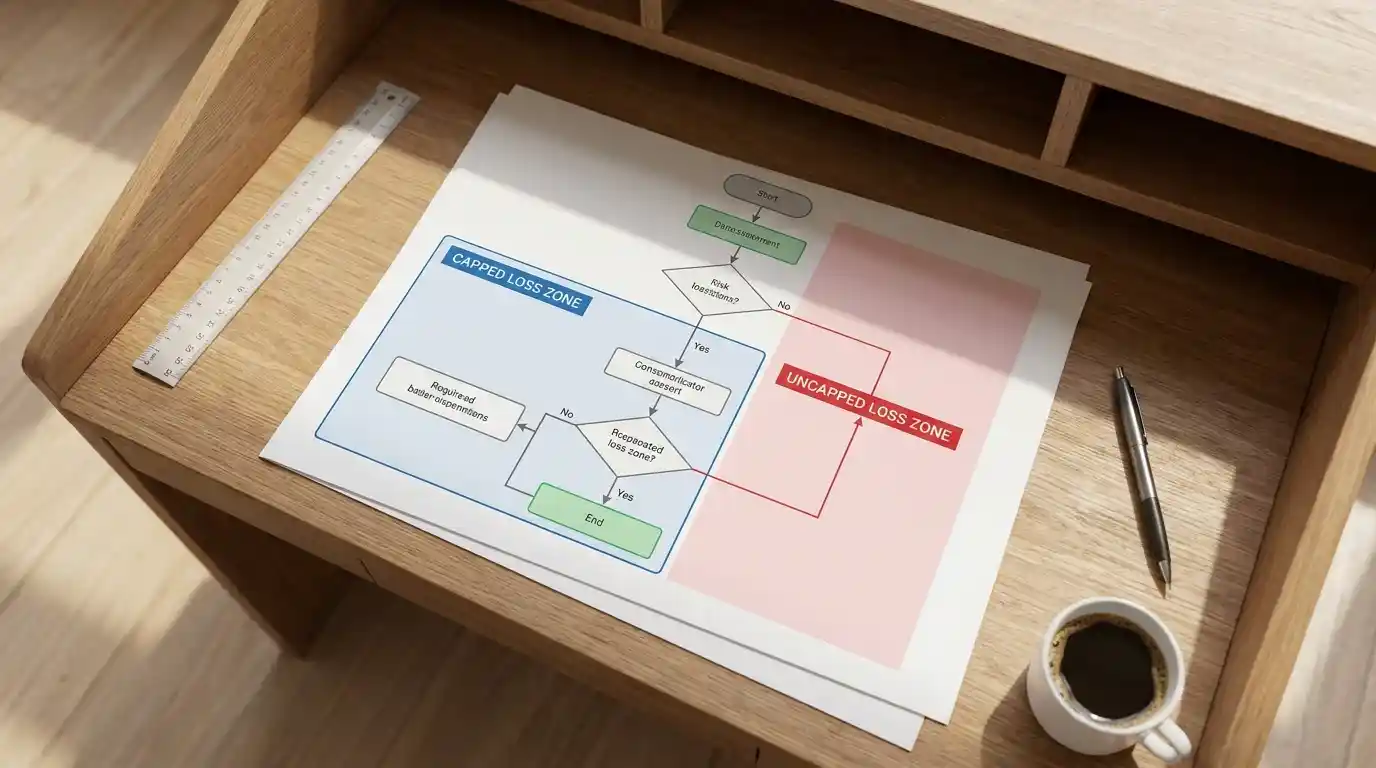
The Problem Gambling Severity Index data from UK regulatory bodies shows that 2.5% of the UK adult population scores in the problem gambling category — and spread betting’s uncapped loss potential makes it a particularly high-risk environment for anyone with an impulsive gambling tendency. I mention this not to be preachy but because the stakes are structurally different: losing ten times your intended stake on a fixed-odds bet is impossible; in spread betting, it is straightforward if you are not disciplined about position sizing.
The most common sizing error I see is staking per point at a level that makes a bad position feel like a smaller problem than it is. A £10 per point position on a finishing position spread does not feel large when you open it — but if your player finishes 60th rather than the implied 10th, the realised loss is £500. Keep your per-point stake at a level where a worst-case finishing position in a 156-player field represents a loss you have budgeted for and accepted in advance.
For the bankroll framework that applies across all forms of systematic golf betting, the golf betting bankroll management guide covers unit sizing, drawdown limits, and staking plan structures that adapt to high-variance products like spread betting.
Is golf spread betting regulated by the FCA or the Gambling Commission?
Golf spread betting in the UK is regulated by the Financial Conduct Authority, not the Gambling Commission. Spread betting is classified as a financial derivative product, which brings it under FCA conduct rules including capital adequacy requirements, client money protection rules, and mandatory risk disclosure. This is a meaningful distinction: the FCA framework provides different consumer protections than the Gambling Commission regime, and operators offering spread betting are not subject to the statutory gambling levy introduced in 2025 for licensed gambling operators.
What is the supremacy market in golf spread betting?
The supremacy market measures the total stroke difference between two players or two sides (such as USA vs Europe in a team event) over the full course of a tournament or match. You buy the supremacy spread if you think the margin will be wider than the operator implies; you sell if you think it will be narrower. The settlement value is the actual stroke or point difference, and your profit or loss is that difference from your entry price multiplied by your stake. Supremacy markets are common in Ryder Cup betting, where the points margin of victory is the traded variable.
This material was created by SwingEdge team.
